Wednesday, March 5, 2014

Breaking: Estonian Foreign Minister Urmas Paet and Catherine Ashton disc .... | "Behind The Kiev Snipers It Was Somebody From The New Coalition" - A Stunning New Leak Released


The last time a leaked phone call out of Ukraine was released about a month ago ostensibly by the Russian NSA equivalent, one between US assistant sec state Victoria Nuland and the US envoy to the Ukraine, Geoffrey Pyatt, it was revealed that the real puppet masters behind the Maidan movement, and the true instigators of the Ukraine "revolution" were none other than the "developed" world superpowers, lead by the US. Also revealed were tensions between the US and EU strategies on how to overthrow the current government, culminating with the infamous "Fuck the EU." Needless to say the US, which implicitly confirmed the recording, was angry at Russia and accused it of using dirty tricks.

That's ironic, because when it comes to "dirty tricks" what is about to be presented, blows the top off anything Russia may or has done to date.

Earlier today an even more shocking recording has been "leaked" this time one between the always concerned about human rights EU foreign affairs chief Catherine Ashton and Estonian foreign minister Urmas Paet, in which it is revealed on tape that all those photos of horrifying deaths of Ukrainians by snipers during the last days of the Median stand off, were in fact caused not by Snipers controlled by Yanukovich, but that the snipers shot at both protesters and police in Kiev were allegedly hired by Maidan leaders!
Ashton: "I think we do want to investigate. I mean, I didn’t pick that up, that’s interesting. Gosh."


Here is the key exchange, just after 8 minutes into the conversation :

Paet: "All the evidence shows that people who were killed by snipers from both sides, policemen and people from the streets, that they were the same snipers killing people from both sides. ... Some photos that showed it is the same handwriting, the same type of bullets, and it is really disturbing that now the new coalition they don't want to investigate what exactly happened.


So there is now stronger and stronger understanding that behind the snipers, it was not Yanukovych, but it was somebody from the new coalition."


Paet: "It already discreditates (sic) this new coalition."

So first US orchestrates the Kiev overthrow, and now the new "leaders" of Ukraine are allegedly found to have fired against their own people - the same provocation they subsequently used to run Yanukovich out of the country and install a pro-Western puppet government. Of course, said pro-Western coalition has not been discreditated (sic) because Ms. Ashton has sternly refused to investigate, knowing quite well how horribly this would reflect on the new Ukraine "leadership" -  a government which shot its own people to fabricate the pretext under which it rose to power.

Is it any wonder then that Russia has responded the way it has?

As for at least one of the affected parties, Estonia, it has just confirmed the authenticity of the recording, and the ministry of foreign affairs has organized a press conference to answer media questions today at 5 pm.

From the Valisministeerium:
No. 84-E Foreign Minister Urmas Paet and EU foreign policy chief Catherine Ashton uploaded to the Internet today, a phone call is authentic.

Paet and Ashton conversation took place on 26 February, following Estonia's Foreign Minister's visit to Ukraine, and immediately after the end of the street violence.

Foreign Minister Paet communicate what he had said about the meetings held in Kiev last day and expressed concern about the situation.

"It is extremely regrettable that such an interception is occurring at all""said Paet., Including its call for today's photos are not random," he added.
Yes, it is truly regrettable that the people know the truth.

http://www.zerohedge.com/news/2014-03-05/behind-kiev-snipers-it-was-somebody-new-coaltion-stunning-new-leak-reveals-truth<<

Tyler Durden's picture


l


TOP 10 SIGNS THAT REVEAL MOUNTING PANIC IN THE WORLD BANKING SYSTEM | BANKERS TELL IT LIKE IT IS | TOP 10 QUOTES THAT REVEAL THEIR CRIMES


http://www.libertygoldandsilver.com/GoldandSilverBlog/wp-content/uploads/2014/03/BankerExecRunning.jpgPosted on March 4, 2014 by Liberty Staff   

BankerExecRunning
The alternate financial media has been abuzz of late with bizarre stories of the alleged suicides of prominent members of world banking and finance. Over recent weeks, between eight and twelve (some say as many as twenty) successful traders and managers involved with FOREX trading and other derivative currency speculation, have conveniently “decided” to throw themselves from the roof tops of a variety of JP Morgan Chase banks in London, Hong Kong, and New York. Another top banking official, William Broeksmit, former executive at Deutsche Bank, was found hanged in his London home.

And others with strong connections to investment banking and the Federal Reserve itself have likewise met unusual deaths. Michael Dueker, former vice president of the St. Louis branch of the Federal Reserve, was found at the bottom of a fifty foot embankment below where he had just parked his car in Tacoma, Washington. The cause of death is still undetermined. The strangest of these deaths was Richard Talley, a former investment banker with Drexel Burnham Lambert who was alleged to have shot himself with a nail gun at least ten times in his Centennial, Colorado, home.

The keen observer will note that a great number of these deaths have occurred in tandem with the extensive multinational regulatory agency investigations of egregious fraud, price fixing, and “front run” trading in the FOREX markets and in the LIBOR index. These markets are gigantic and it is hard for the novice to comprehend the magnitude of money that is involved in daily transactions for both of these. The weekly volume on the FOREX market alone is excess of $20 trillion.

As of two weeks ago, no less than ten global banking giants including JP Morgan Chase, Royal Bank of Scotland, Deutsche Bank, Goldman Sachs, Credit Suisse, Lloyds Banking Group, and others, have found themselves the object of a litany of criminal probes that undoubtedly have created tension and fear, bordering on “flight or fight” panic within these banking conglomerates. Only the extremely naïve could find it hard to believe that the banking world, in order to cover up and protect itself from prosecution of the greatest financial crimes and frauds in history, would not resort to measures of extreme prejudice to eliminate potential material witnesses.

The key point to understand here, however, is that this is not at all a new phenomenon. The history of banking in the modern era (since the establishment of the Bank of England in the late 17th century), has been nothing but an ugly cavalcade of theft of sovereign national treasuries too vast to calculate. From the beginning, these large private central banks (the Bank of England, the Federal Reserve, the Bank of Japan, etc.), were intentionally designed to operate freely above the rule of law in their respective nations. They have been the financiers of most of the conflicts and wars in the last two centuries and are continuing to do so unabated to the present. Countless millions have died in these bankers’ wars in service to the unbridled greed of these financiers.

Through the massive inflation of each nation’s currency they dominate, the bankers have robbed the citizens of the purchasing power of their money and with it, their life savings. Since the establishment of the Federal Reserve in 1913, for example, the purchasing power of the US dollar has been eroded to nearly 1/100th of its original value. This has not been accidental. This was planned from the beginning. Private fractional reserve central banking is the greatest criminal conspiracy that continues to this day to hide in plain sight.

But please, don’t just think this is only our opinion. Fascinatingly, the bankers themselves have throughout the decades, clearly revealed their purpose and intent. At this juncture, we would like to offer some quotes for you by the highest ranking members of the banking elite, past and present.

“The bank hath benefit of interest on all moneys which it creates out of nothing.”  William Paterson, founder of the Bank of England in 1694

“Let me issue and control a nation’s money and I care not who writes the laws.”  Mayer Amschel Rothschild (1744-1812), founder of the House of Rothschild.

“If my sons did not want wars, there would be none.”  Gutle Schnaper, wife of Mayer Amschel Rothschild and mother of his five sons

“The few who understand the system will either be so interested in its profits or be so dependent upon its favours that there will be no opposition from that class, while on the other hand, the great body of people, mentally incapable of comprehending the tremendous advantage that capital derives from the system, will bear its burdens without complaint, and perhaps without even suspecting that the system is inimical to their interests.”  The Rothschild brothers of London writing to associates in New York, 1863

 “Banking was conceived in iniquity and was born in sin. The Bankers own the Earth. Take it away from them, but leave them the power to create deposits, and with the flick of a pen they will create enough deposits to buy it back again. However, take it away from them, and all the fortunes like mine will disappear, and they ought to disappear, for this world would be a happier and better world to live in. But if you wish to remain slaves of the Bankers and pay for the cost of your own slavery, let them continue to create deposits.”  Sir Josiah Stamp, President of the Bank of England in the 1920s, the second richest man in Britain

“When you or I write a check, there must be sufficient funds in our account to cover the check; but when the Federal Reserve writes a check, there is no bank deposit on which that check is drawn. When the Federal Reserve writes a check, it is creating money.”  From the Boston Federal Reserve Bank pamphlet, “Putting it Simply.”

“Neither paper currency nor deposits have value as commodities. Intrinsically, a ‘dollar’ bill is just a piece of paper. Deposits are merely book entries.”  “Modern Money Mechanics Workbook” – Federal Reserve of Chicago, 1975

 “I am afraid the ordinary citizen will not like to be told that the banks can and do create money. And they who control the credit of the nation direct the policy of Governments and hold in the hollow of their hand the destiny of the people.”  Reginald McKenna, as Chairman of the Midland Bank, addressing stockholders in 1924

“I am just a banker doing God’s work.”  Lloyd Blankfein, CEO, Goldman Sachs, 2009

“Banks do not have an obligation to promote the public good.”  Alexander Dielius, CEO, Germany, Austrian, Eastern Europe Goldman Sachs, 2010

So there it is in their own words. The arrogance, elitism, and condescension of bankers towards the common citizen are starkly revealed. These brilliant criminals have created the Ponzi scheme of all Ponzi schemes and so far, protected it from any form of criminal prosecution. However, that might be about to change. Awareness of their criminality is growing throughout the world at a rapid pace but never doubt that this group will fight tenaciously and be willing to go to any extremes to protect their centuries’ old scam. We predict there will undoubtedly be more strange banker deaths ahead of us in the ensuing weeks, months, and years.

The next time you walk into your local bank, please ask yourself this question, “Do I really want to entrust my hard earned wages and savings to a centuries’ old criminal scheme?” If you don’t, please consider gold and silver for protection of your wealth.”

To learn more about the rewards of precious metals investing, including how to fund your existing IRA with gold or silver, call Liberty Gold and Silver seven days a week at 888.751.3330. To learn about the most generous affiliate marketing program in the precious metals industry, please visit the Liberty Gold and Silver Affiliate Marketing Program. We're happy to spend as much time as you need to discuss the details with you.

© Copyright 2013 Liberty Gold and Silver, All rights Reserved.  Written For: Liberty Gold and Silver News Blog  http://www.libertygoldandsilver.com/GoldandSilverBlog/?p=385<<

'How did these guys get in the Army?' New study delves into mental illness

Reuters / Andrew Burton

March 05, 2014
Reuters / Andrew Burton  |  About one in five US soldiers have been found to have a common mental illness such as depression or panic disorder upon enlisting in the Army, according to a new study.

A second study showed that over eight percent of soldiers had contemplated suicide and 1.1 percent had attempted suicide, researchers found via confidential surveys and interviews with 5,428 soldiers at Army bases across the US.

The studies’ results were published on Monday in JAMA Psychiatry. Experts say the findings show a weakness in recruiting processes. Army applicants are asked about their psychiatric pasts in evaluations, while those with certain disorders or a history of suicide attempts are often kept from entering the service.

Another separate study of one million soldiers from 2004 to 2009 found that those who had been deployed to Afghanistan or Iraq had an increased rate of suicide.

The studies are the first released as part of a large research initiative that began in 2009 by the Army and the National Institute of Mental Health in response to a spate of suicides in the armed forces. In 2011, a representative sample of soldiers was assessed for eight common psychiatric disorders.

Researchers found that soldiers interviewed had joined the Army with higher rates of post-traumatic stress disorder (PTSD), panic disorder, and attention deficit and hyperactivity disorder (ADHD) than the general population.

"The question becomes, 'How did these guys get in the Army?'" Ronald Kessler, a Harvard University sociologist and leader of one of the studies, said to the Los Angeles Times.

The studies found that over eight percent of soldiers came into the Army with intermittent explosive disorder, marked by unrestrained anger attacks. It was the most common disorder found, as pre-enlistment levels were six times the civilian rate.

Pre-enlistment rates of depression, anxiety, bipolar disorder, and substance abuse were found to be close to civilian rates. Suicidal ideation, planning, and attempt rates fell under the general population rate, though still significant.

Though during military service, the surveyed soldiers’ rates of psychiatric disorders climbed well beyond civilian levels and far beyond the normal rate for some disorders.

A quarter of soldiers were found to be suffering from a mental illness: around five percent with depression, around six percent with anxiety disorder, and almost nine percent with PTSD.

The amount of soldiers who had attempted suicide went up from 1.1 percent to 2.4 percent, though the study did not explain a possible cause.

Harvard University’s Matthew Nock, leader of the suicide study, said that over 30 percent of suicide attempts after enlistment would not have occurred if the Army had nixed recruits who were found to have pre-existing psychiatric disorders.

He recommends stricter screening standards for recruits, though other experts are not certain that the solution is so simple.

"People who want to come into the Army are no fools," said Dr. Elspeth Ritchie, a former chief psychiatrist in the Army. "They know if you say you had a past suicide attempt, you're probably not going to get in."
 
The Pentagon has not commented on the studies.   Get short URL<<

>>  http://theartof12.blogspot.com/2014/02/which-corporations-control-world-worlds.html

>> http://theartof12.blogspot.com/2013/12/steve-forbes-father-was-allegedly.html

>>  http://theartof12.blogspot.com/2014/01/ben-cardin-d-md-myrna-year-of-horse.html

>>  http://theartof12.blogspot.com/2014/01/jihad-usa-military-global-new-scandals.html

>>  http://theartof12.blogspot.com/2014/02/us-bankruptcy-court-district-of-oregon.html

>>  http://theartof12.blogspot.com/2014/02/the-clinton-pinchuk-connection.html

>>  http://theartof12.blogspot.com/2013/02/march-4-2013-forbes-issue-two-awful.html

[sidebar:  CRIMINALLY INSANE "Homo Sapiens" DO NOT become sane.  The more that the predatory are given the GREEN GO AGENDA 21 APARTHEID-GENOCIDE, the World Earth is NOT O.K. and there shall be a return to a balance which the CRIMINALLY INSANE aren't capable in the damaged bodies, minds, spirits, to comprehend obviously!]

.. to be continued ...

Forbes 400 List of World’s Richest People Highlights Growth of Social Inequality | HEIGHT-WIDTH-BREADTH-LENGTH-DEPTH ~MEASURING TOTALIARIAN-PSYCHOPATHY

Wealth And Inequality In America: The Rich are getting Richer and the Poor are getting Poorer
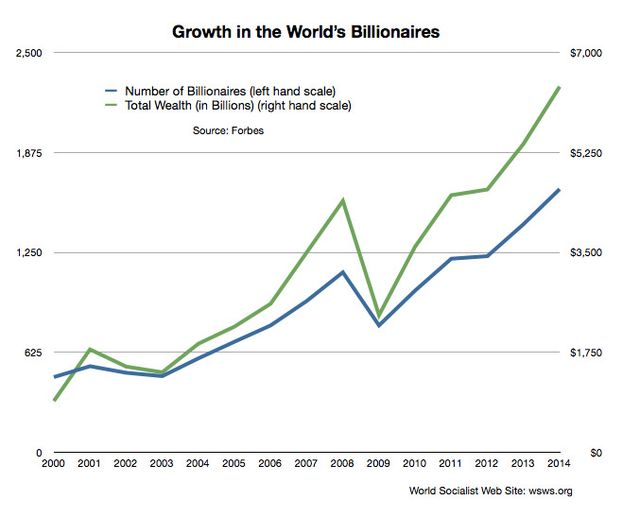
Forbes magazine published its 28th annual list of the world’s wealthiest individuals and families on Monday. In all, the research team behind the Forbes Billionaires list found a total of 1,645 billionaires worldwide as of February 12, with a combined net worth of $6.4 trillion, an increase of $1 trillion from 2013. The number of new billionaires, at 268, was the highest figure in the report’s history.

A surge in equity markets resulting from the ultra-loose money policies of the US Federal Reserve pushed the total number of American billionaires to 492, the highest of any nation. China, the foremost cheap labor platform in the global economy, boasts the second highest number of billionaires at 152. The Russian Federation, politically dominated by a narrow layer of compradors who liquidated the USSR and plundered its state assets in 1990-91, rounded out the top three nations, with 111 billionaires.
Around 100 people lost billionaire status, including 19 in Turkey, where a reversal of foreign investment flows has dashed the stock indexes and the currency, as have eight individuals in Indonesia due to the same global financial imbalances caused by the US Federal Reserve’s policies. Algeria, Lithuania, Tanzania and Uganda all saw their first appearances on the Forbes list, and Nigeria’s Aliko Dangote became the first African to make the top 25, with a fortune of $25 billion.

Microsoft founder and charter school champion Bill Gates has become the wealthiest individual in the world once again, with a yearly growth in his personal fortune of $9 billion and a total net worth of $76 billion, a sum more than four times larger than the entire municipal debt of the city of Detroit, or, stated another way, enough money to pay for four years of state college tuition in the US for 2.1 million students.

Other Internet-related persons featured prominently on the Forbes list, including Facebook CEO Mark Zuckerburg, whose fortune nearly doubled this year from $15.2 billion to $28.5 billion. Zuckerberg was the year’s biggest dollar gainer thanks to the soaring value of Facebook shares, which increased over 130 percent in the last 12 months. Facebook’s COO Sheryl Sandberg made the list as well, as did the company’s vice president Jeff Rothschild.

The year 2013 saw windfall compensation for executives of top private equity firms, cashing in on record share values and awarding generous dividends to their investors and to themselves. A Wall Street Journal article this week, headlined “Blowout Haul for Buyout Tycoons , ” examined public filings for Apollo Global Management LLC, Blackstone Group LP, KKR and Co., and the Carlyle Group LP. The article reports that the nine founders of these firms took in a total of $2.6 billion in 2013, a year-on-year increase of more than 100 percent. This amount averages over $160 million for each of the executives in question, enough to pay the starting salary of nearly 3,500 public school teachers in New York City for one year.

Of this elite, parasitic group, Leon Black, the co-founder and chief executive of Apollo Global Management, raked in the most at $546.3 million, followed by Blackstone Group’s Stephen Swarzman with $465.4 million. The three co-founders of Washington, DC-based Carlyle Group pocketed a total of nearly $750 million, more money than was spent on all of the district’s capital outlays for public schools between 2005 and 2008. Unlike the corporate giants of a previous era, which at least built railroads, factories and infrastructure, the highly profitable private equity funds that nourish today’s robber barons excel in the wholesale dismantling of entire sections of industry, buying companies or public entities, laying off the bulk of their workers, and then selling them at a profit as “competitive” enterprises.

The exploding fortunes of the world’s richest people in the last decade and a half are a consequence of a deliberate assault on the living standards of working people, including the slashing of social spending, declining real wages and almost unprecedented layoffs. A number of striking figures illustrate this fact:
* The world’s 85 richest people have more wealth than the poorer half of the world’s population combined. Some 2.4 billion people live on less than $2 per day.

* In the United States, 95 percent of all income gains between 2009 and 2012 went to the wealthiest 1 percent of the population. The proportion of income held by this layer has grown by nearly 150 percent since 1980. New records for unemployment, inequality and social misery are set on a regular basis.

To juxtapose the enormous and growing opulence at the top of society on the one hand, with the increasingly wretched, untenable position of most of the world’s population on the other, is to pose the necessity of socialism. Plainly said, society cannot afford the financial aristocrats, who make the feudal monarchs of the past look modest by comparison.


Tuesday, March 4, 2014

A Storm is Brewing on the Horizon – Will Obama Declare Martial Law Before 2016?

http://freedomoutpost.com/2014/03/storm-brewing-horizon-will-obama-declare-martial-law-2016/#7eJyTJ4mW7qc4MPc.99


Russia warns could 'reduce to zero' economic dependency on US

Moscow (AFP) - Russia could reduce to zero its economic dependency on the United States if Washington agreed sanctions against Moscow over Ukraine, a Kremlin aide said on Tuesday, warning that the American financial system faced a "crash" if this happened.

"We would find a way not just to reduce our dependency on the United States to zero but to emerge from those sanctions with great benefits for ourselves," said Kremlin economic aide Sergei Glazyev.

He told the RIA Novosti news agency Russia could stop using dollars for international transactions and create its own payment system using its "wonderful trade and economic relations with our partners in the East and South."

Russian firms and banks would also not return loans from American financial institutions, he said.
"An attempt to announce sanctions would end in a crash for the financial system of the United States, which would cause the end of the domination of the United States in the global financial system," he added.
He said that economic sanctions imposed by the European Union would be a "catastrophe" for Europe, saying that Russia could halt gas supplies "which would be beneficial for the Americans" and give the Russian economy a useful "impulse".

Glazyev has long been seen as among the most hawkish of the advisors to President Vladimir Putin but many observers have seen his hand in the apparent radicalisation of policy on Ukraine since the overthrow of president Viktor Yanukovych.

Economists have long mocked his apocalyptic and confrontational vision of global economics but also expressed concern that he appears to have grown in authority in recent months.

A high ranking Kremlin source told RIA Novosti that Glazyev was speaking in the capacity of an "academic" and his personal opinion did not reflect the official Kremlin policy.

Glazyev descrived the new Ukrainian authorities as "illegitimate and Russophobic", saying some members of the government were on lists of "terrorist organisations, they are criminals".

"If the authorities remain criminal then I think the people of Ukraine will get rid of them soon," he added.


JPMorgan Chase Engaged in Mortgage Fraud. The Securitization Fraud That Collapsed the Housing Market The Stone that Brings Down Goliath? Richmond and Eminent Domain

bankster-chess
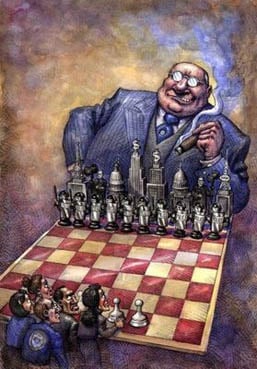
In a nearly $13 billion settlement with the US Justice Department in November 2013, JPMorganChase admitted that it, along with every other large US bank, had engaged in mortgage fraud as a routine business practice, sowing the seeds of the mortgage meltdown. JPMorgan and other megabanks have now been caught in over a dozen major frauds, including LIBOR-rigging and bid-rigging; yet no prominent banker has gone to jail. Meanwhile, nearly a quarter of all mortgages nationally remain underwater (meaning the balance owed exceeds the current value of the home), sapping homeowners’ budgets, the housing market and the economy. Since the banks, the courts and the federal government have failed to give adequate relief to homeowners, some cities are taking matters into their own hands.

Gayle McLaughlin, the bold mayor of Richmond, California, has gone where no woman dared go before, threatening to take underwater mortgages by eminent domain from Wall Street banks and renegotiate them on behalf of beleaguered homeowners. A member of the Green Party, which takes no corporate campaign money, she proved her mettle standing up to Chevron, which dominates the Richmond landscape. But the banks have signaled that if Richmond or another city tries the eminent domain gambit, they will rush to court seeking an injunction. Their grounds: an unconstitutional taking of private property and breach of contract.

How to refute those charges? There is a way; but to understand it, you first need to grasp the massive fraud perpetrated on homeowners. It is how you were duped into paying more than your house was worth; why you should not just turn in your keys or short-sell your underwater property away; why you should urge Congress not to legalize the MERS scheme; and why you should insist that your local government help you acquire title to your home at a fair price if the banks won’t. That is exactly what Richmond and other city councils are attempting to do through the tool of eminent domain.

The Securitization Fraud That Collapsed the Housing Market

One settlement after another has now been reached with investors and government agencies for the sale of “faulty mortgage bonds,” including a suit brought by Fannie and Freddie that settled in October 2013 for $5.1 billion. “Faulty” is a euphemism for “fraudulent.” It means that mortgages subject to securitization have “clouded” or “defective” titles. And that means the banks and real estate trusts claiming title as owners or nominees don’t actually have title – or have standing to enjoin the city from proceeding with eminent domain. They can’t claim an unconstitutional taking of property because they can’t prove they own the property, and they can’t claim breach of contract because they weren’t the real parties in interest to the mortgages (the parties putting up the money).

“Securitization” involves bundling mortgages into a pool, selling them to a non-bank vehicle called a “real estate trust,” and then selling “securities” (bonds) to investors (called “mortgage-backed securities” or “collateralized debt obligations”). By 2007, 75% of all mortgage originations were securitized. According to investment banker and financial analyst Christopher Whalen, the purpose of securitization was to allow banks to avoid capitalization requirements, enabling them to borrow at unregulated levels.

Since the real estate trusts were “off-balance sheet,” they did not count in the banks’ capital requirements. But under applicable accounting rules, that was true only if they were “true sales.” According to Whalen, “most of the securitizations done by banks over the past two decades were in fact secured borrowings, not true sales, and thus potential frauds on insured depositories.” He concludes, “bank abuses of non-bank vehicles to pretend to sell assets and thereby lower required capital levels was a major cause of the subprime financial crisis.”

In 1997, the FDIC gave the banks a pass on these disguised borrowings by granting them “safe harbor” status. This proved to be a colossal mistake, which led to the implosion of the housing market and the economy at large. Safe harbor status was finally withdrawn in 2011; but in the meantime, “financings” were disguised as “true sales,” permitting banks to grossly over-borrow and over-leverage. Over-leveraging allowed credit to be pumped up to bubble levels, driving up home prices. When the bubble collapsed, homeowners had to pick up the tab by paying on mortgages that far exceeded the market value of their homes. According to Whalen:
[T]he largest commercial banks became “too big to fail” in large part because they used non-bank vehicles to increase leverage without disclosure or capital backing. . . .
The failure of Lehman Brothers, Bear Stearns and most notably Citigroup all were largely attributable to deliberate acts of securities fraud whereby assets were “sold” to investors via non-bank financial vehicles.  These transactions were styled as “sales” in an effort to meet applicable accounting rules, but were in fact bank frauds that must, by GAAP and law applicable to non-banks since 1997, be reported as secured borrowings.  Under legal tests stretching from 16th Century UK law to the Uniform Fraudulent Transfer Act of the 1980s, virtually none of the mortgage backed securities deals of the 2000s met the test of a true sale.
. . . When the crisis hit, it suddenly became clear that the banks’ capital was insufficient.
Today . . . hundreds of billions in claims against banks arising from these purported “sales” of assets remain pending before the courts.
Eminent Domain as a Negotiating Tool

Investors can afford high-powered attorneys to bring investor class actions, but underwater and defaulting homeowners usually cannot; and that is where local government comes in. Eminent domain is a way to bring banks and investors to the bargaining table.

Professor Robert Hockett of Cornell University Law School is the author of the plan to use eminent domain to take underwater loans and write them down for homeowners. He writes on NewYorkFed.org:
[In] the case of privately securitized mortgages, [principal] write-downs are almost impossible to carry out, since loan modifications on the scale necessitated by the housing market crash would require collective action by a multitude of geographically dispersed security holders. The solution . . . Is for state and municipal governments to use their eminent domain powers to buy up and restructure underwater mortgages, thereby sidestepping the need to coordinate action across large numbers of security holders.
The problem is blowback from the banks, but it can be blocked by requiring them to prove title to the properties. Securities are governed by federal law, but real estate law is the domain of the states. Counties have a mandate to maintain clean title records; and legally, clean title requires a chain of “wet” signatures, from A to B to C to D. If the chain is broken, title is clouded. Properties for which title cannot be established escheat (or revert) to the state by law, allowing the government to start fresh with clean title.

New York State law governs most of the trusts involved in securitization. Under it, transfers of mortgages into a trust after the cutoff date specified in the Pooling and Servicing Agreement (PSA) governing the trust are void.

For obscure reasons, the REMICs (Real Estate Mortgage Investment Conduits) claiming to own the properties routinely received them after the closing date specified in the PSAs. The late transfers were done throu gh the fraudulent signatures-after-the-fact called “robo-signing,” which occurred so regularly that they were the basis of a $25 billion settlement between a coalition of state attorneys general and the five biggest mortgage servicers in February 2012. (Why all the robo-signing? Good question. See my earlier article here.)

Until recently, courts have precluded homeowners from raising the late transfers into the trust as a defense to foreclosure, because the homeowners were not parties to the PSAs. But in August 2013, in Glaski v. Bank of America, N.A., 218 Cal. App. 4th 1079 (July 31, 2013), a California appellate court ruled that the question whether the loan ever made it into the asset pool could be raised in determining the proper party to initiate foreclosure. And whether or not the homeowner was a party to the PSA, the city and county have a clear legal interest in seeing that the PSA’s terms were complied with, since the job of the county recorder is to maintain records establishing clean title.

Before the rise of mortgage securitization, any transfer of a note and deed needed to be recorded as a public record, to give notice of ownership and establish a “priority of liens.” With securitization, a private database called MERS (Mortgage Electronic Registration Systems) circumvented this procedure by keeping the deeds as “nominee for the beneficiary,” obscuring the property’s legal owner and avoiding the expense of recording the transfer (usually about $30 each). Estimates are that untraceable property assignments concealed behind MERS may have cost counties nationwide billions of dollars in recording fees. (See my earlier article here.)
Counties thus have not only a fiduciary but a financial interest in establishing clean title to the properties in their jurisdictions. If no one can establish title, the properties escheat and can be claimed free and clear. Eminent domain can be a powerful tool for negotiating loan modifications on underwater mortgages; and if the banks cannot prove title, they have no standing to complain.

The End of “Too Big to Fail”?

Richmond’s city council is only one vote short of the supermajority needed to pursue the eminent domain plan, and it is seeking partners in a Joint Powers Authority that will make the push much stronger. Grassroots efforts to pursue eminent domain are also underway in a number of other cities around the country. If Richmond pulls it off successfully, others will rush to follow.

The result could be costly for some very large banks, but they have brought it on themselves with shady dealings. Christopher Whalen predicts that the FDIC’s withdrawal of “safe harbor” status for the securitization model may herald the end of “too big to fail” for those banks, which will no longer have the power to grossly over-leverage and may have to keep their loans on their books.

Wall Street banks are deemed “too big to fail” only because there is no viable alternative – but there could be. Local governments could form their own publicly-owned banks, on the model of the state-owned Bank of North Dakota. They could then put their revenues, their savings, and their newly-acquired real estate into those public utilities, to be used to generate interest-free credit for the local government (since it would own the bank) and low-cost credit for the local community. For more on this promising option, which has been or is being explored in almost half the state legislatures in the US, see here.

Ellen Brown is an attorney, president of the Public Banking Institute, and a candidate for California State Treasurer running on a state bank platform. She is the author of twelve books including the best-selling Web of Debt and her latest book, The Public Bank Solution, which explores successful public banking models historically and globally.  Web of Debt
http://www.globalresearch.ca/jpmorgan-chase-engaged-in-mortgage-fraud-the-securitization-fraud-that-collapsed-the-housing-market/5371764

Return of the Idiot Savant: John Kerry Tries to Weigh-in on ‘The Ukraine Crisis’

He’s not exactly the brightest spark, but he has certainly distinguished himself as the new unofficial leader of Washington’s new Hypocrite Society.

You thought you’d seen the worst of it when he fumbled the Syria debacle, trying it on with WMD fictional tale, kicking the ball into his own net as he bluffed military intervention only to be out-foxed by his Russian counterpart Sergey Lavrov. Well, he’s back, and weaker than ever…

Astonishingly, US Secretary of State John Kerry said today: “You just don’t invade another country on phony pretext in order to assert your interests,” John Kerry said during an interview with NBC’s Meet the Press. “This is an act of aggression that is completely trumped-up in terms of its pretext. It’s really 19th century behaviour in the 21st century.”

Before that, Kerry barked in a roundtable interview with reporters saying, “I don’t think there should be any doubt whatsoever that any kind of military intervention that would violate the sovereign territorial integrity of Ukraine would be a huge — a grave — mistake”.

Sound familiar? Kerry echoed the same hollow bluff in the run-up to war with Syria only 6 months ago.

OREGON FRAUDULENT INDUCEMENT & TRANSFERENCE OF WEALTH? || JEWS' FORKED WAGGING TONGUES' KILLING TIME

Cover Oregon health insurance exchange fiasco spawns problems for low-income Oregonians' health plan

CoverOROct1byBudnick.JPG
Problems with the Cover Oregon health insurance exchange have spilled over into the state's low-income health plan. The exchange's promised Medicaid interface remains unfinished. (Nick Budnick / The Oregonian)  http://www.oregonlive.com/health/index.ssf/2014/03/cover_oregon_health_insurance_1.html March 01, 2014 
Nearly 4,000 applicants for a state program that provides undocumented immigrants with pregnancy services were instead enrolled in full Oregon Health Plan coverage, contrary to federal law, thanks to problems with the Cover Oregon health insurance exchange.

State officials say they discovered the problem several weeks ago and are correcting it.

The pregnancy program goof, however, is just one of many little-known problems that Oregon Health Plan members, providers, care groups and state officials have wrestled with as Oregon’s system for enrolling people undergoes chaotic change.

It’s the flip side of the Cover Oregon debacle, where much of the attention has focused on the travails of people applying for private or commercial insurance.

Two thirds of Cover Oregon’s enrollments -- more than 70,000 -- have gone into the low-income Oregon Health Plan, the state’s version of Medicaid. Combined with other enrollments since Oct. 1, OHP membership has swelled by more than 200,000, or about a third  -- a favorite talking point of state officials.

Many of those enrollments, however, have not gone smoothly:
  • Thousands of OHP enrollees were labeled as individuals rather than family members, meaning some families were split between care organizations – creating needless hassles for parents seeking care.
  • For months, the state grappled with inaccurate Medicaid coding, crucial to securing accurate federal matching funds.
  • Department of Human Services workers who used to help clients afflicted by erroneous information now face difficulties doing so because their responsibilities have been transferred to Cover Oregon.
Some of the problems with OHP enrollments are due to limitations with the Cover Oregon exchange information technology. Others stem from flaws in the many “workaround” band-aid systems set up to patch for problems with the exchange. Officials say they are working through these issues slowly and attribute them to standard growing pains.

“It never works perfectly the first time out,” said Kathleen Paul, an Oregon Health Authority manager who has worked on the Cover Oregon information-technology project.

The Cover Oregon health insurance exchange was designed to communicate electronically with the Oregon Health Authority, which has a system for tracking Oregon Health Plan members.

That interface failed to work, however, and in late November Cover Oregon set up a backup system by which new OHP enrollee information is sent to the Oregon Health Authority, where state workers upload the data manually.

The information was sent over incorrectly and in an incomplete fashion until a few weeks ago, Paul said Friday. That resulted in 3,800 applicants for the Citizen/Alien-Waived Emergent Medical program receiving full OHP benefits instead.  The program is set up for immigrants who are either undocumented or haven’t met the residency requirement for Medicaid.

 “We were just getting people into the services,” Paul said, adding that the state will finish fixing the problem in the coming week.

Not only that, but Cover Oregon sent over names of thousands of Oregon Health Plan enrollees as individuals, rather than labeling them properly as families. In some cases this has caused some family members to be assigned to one care organization and provider group while others are assigned to a completely different one.

Paul says that problem is being fixed manually on a case-by-case basis.

“It’s been a mess for us,” said Jeff Heatherington, CEO of Family Care, Inc., one of the organizations that cares for Oregon Health Plan members in the Portland area. “It makes it very difficult for us to tie families together in our database. We can’t identify them, so we have to go through and set up a new data structure internally and then match addresses -- all of which have been hand-entered so they don’t necessarily match.”

Jan Buffa, CEO of the Willamette Valley Providers Health Authority, an OHP provider organization based in Salem, says her group has seen fewer problems, but has been perturbed by mysterious fluctuations in its member rolls maintained by the Oregon Health Authority.

“We had a few hundred people disappear off of our enrollment, and (OHA) couldn’t explain it,” she said.  “We’ve been waiting patiently for their explanation.”

Another problem: Oregon Health Authority workers have had to send out federally required notices to OHP members by hand, rather than in the automated way originally intended.

Many of the problems faced by OHP clients filter down to the caseworkers and eligibility specialists who staff the offices of the Department of Human Services, which used to handle enrollment before the exchange came along.

There, workers used to be able to fix problems such as address changes or incorrect information. But now, under the new system, they are largely denied the ability to change files to correct the many problems clients are reporting.

 “It’s a very confusing and trying time right now,” said Jan Mautz, an eligibility analyst for the Oregon Health Authority, who says the situation was “horrendous” but is improving. She spoke through the Service Employees International Union, which represents Mautz and other caseworkers. “We're trying our best to get people through the broken system. The systems don’t talk to each other.”

Lawmakers recently received an anonymous letter from state employees detailing a dozen such problems affecting tens of thousands of enrollees, including that the new IT system used by the Oregon Health Authority for OHP doesn’t properly calculate the code used to determine federal matching funds. “Medicaid has suffered an assault (and) is bleeding profusely,” the letter said.

Paul says there have been problems with the Medicaid code cited, but they’ve been recently fixed and stemmed not from the technology, but how the system was programmed. She said the letter reflects a misunderstanding of many of the issues, and many of the problems have been resolved.

“Things are different than they used to be, and that is presenting challenges for staff,” she said.

The agency is slowly making progress, officials stressed. For instance, a backlog of 30,000 applications and change orders that existed in late January has been whittled down to about half that figure.

Donald White, a spokesman for the Office of the Inspector General for the U.S. Department of Health and Human Services, said he couldn’t comment on the allegations made by the anonymous state employees.

 “Until we have the results of an investigation, or at least a request for an investigation, there’s not much that I could actually say,” White said. “To the degree that there is HHS grant money involved, of course the Office of the Inspector General is very interested in pursuing the facts of this matter.”
 
--Nick Budnick

[sidebar:  The State of Oregon has about only the OREGONIAN to feed the poor individuals in the State nothing but, the JEWS' FORKED WAGGING TONGUES' KILLING TIME!  So while the IMMIGRANT POPULATION was brought to America, AGAIN, nothing new here, NEW AMSTERDAM that would be NEW YORK NEW YORK, built a WALL on a STREET and did to the INDIANS the exact same Apartheid - Genocide and Hitler used the model and here we go again with the JEWS' FORKED TONGUE OREGONIAN KILLING ALL THAT MOVES, except what OBEYS the NEW WORLD ORDER.  And we can now assess what this looks like.  PILGRIMS are migrated to destroy the societies of PILGRIMS over and over and over.  When do we choose to be a higher intelligent form here?  Not with the KITZHABER "Nazi Cult" allowed to be in charge, PORTLAND CITY had Chief of Police Kruger in the power position and the NAZI ROCKY BUTTE CULTISTS' are very clever in how they fraudulent induce and then transfer all wealth -- MEDICARE-OBAMACARE does not matter the name of the FRAUD is FRAUD, just as the DIGITAL so called 'money'.  Virtual fraud is the 21 Century demon to avoid.

JUST SAY NO to Orygone's FRAUD from early-mid-late ? 1950s!!]

Putin Already Won In Ukraine | "Jew York Times" || 'Jew Forked Wagging Tongue Slimes' Time'!


Putin Already Won In Ukraine
By Brother Nathanael Kapner March 3, 2014 ©
The Brother Nathanael Foundation, PO Box 1242, Frisco CO 80443
E-mail: brothernathanaelfoundation@yahoo.com
___________________________________
WITHOUT A SHOT being fired, Putin has secured a thorough purge of Ukrainian authority from the Autonomous Republic of Crimea (ARC).

As home to Russia’s Black Sea Fleet in the port of Sevastopol, Putin can now be assured that his access to Egypt, Syria, and Iran—wherein his opposition to the agenda of the Jew-ruled West is bearing fruit—will not be compromised.

Contrary to reports by the Jew York Times, Putin NEVER “invaded” or “besieged” Ukraine.

It has been proven, ironically by the same Jew York Times, that Crimean “provisional armed forces” of the ARC and NOT Russian soldiers are the ones guarding sensitive infrastructure entities in the peninsula.

Indeed, the provisional army is made up of Crimea’s own home boys…in their apparently brand new uniforms bought from Russia.

As for Russian soldiers patrolling sensitive areas in Sevastopol and Crimea, CIA Director John Brennan briefed lawmakers today that Russia’s military movements in Ukraine is “permitted” under a 1997 treaty between the two neighbors that allows as many as 25,000 Russian troops in the Crimean region.

“The number of Russian troops that have surged onto the Ukrainian peninsula in recent days remains well below the 25,000 threshold,” Brennan affirmed.

The Crimean government, although it sacked the Kiev-based regional government, will remain part of Ukraine but will strengthen its autonomy as a “federated” republic.

Until the amended constitutional referendum is voted on at the end of March, Crimea remains a provisional autonomous government.

Here’s the lay of the geopolitical land in Ukraine:

1) With Putin upholding regional and international treaties;

2) With the Crimean government organizing its own Defense Ministry;

3) With Ukraine’s Navy Commander Berezovsky pledging an oath to the Crimean people;

4) With an entire Ukraine Air Force Base switching allegiance to Crimea, refusing to take orders from the new, self-appointed government in Kiev;

5) With Ukraine military units refusing orders from the illegitimate regime in Kiev;

6) With the EU unlikely to match the US in threatening sanctions against Russia;

7) With Odessa and two other southern Ukrainian capitals expressing willingness to become a part of the ARC…all that’s left for Putin to do is to put the screws on Kiev and his work is finished.

BOTTOM LINE: Kiev better make friends with Putin fast.

Putin insists that the illegitimate regime in Kiev MUST comply with the EU-brokered February 21st Agreement which insures a lawful government until the agreed-upon December elections.

The people of Ukraine need to prevent Yats the Yid, Nuland’s Yiddishe boy in Kiev, from enslaving them to the Jew-owned IMF.

Better things are ahead for Ukraine with Christian Putin than with Christ-Crucifying Jews.


http://theartof12.blogspot.com/2014/03/ukraine-ueuirael-greatest-mistake-in.html<<